
Most managers expect tokenizing a fund to mean rebuilding it. It doesn't. The fund stays the same fund, with the same manager, depositary, valuation and investor rights. What goes on-chain is the unit: how it is issued, who may hold it, how it moves and how payouts reach the holder.
That makes it different from a crypto-native project in two ways. A protocol writes its own rules, but a licensed manager inherits them, because a fund unit is already a regulated financial instrument. And very little of the work is the token. Most of it is the fund's operations, such as subscriptions, the net asset value (NAV), redemptions, distributions and the depositary's view of all of them.
Who this is for. Licensed asset managers and investment firms tokenizing units of a fund they manage, and the product, engineering and compliance leads behind that decision. This guide covers funds under EU rules. Outside the EU the engineering is similar, but the legal framework is not. If you own a single asset and nobody manages pooled capital, you are on a different path, covered at the end of this guide. No fund owes everything below, so the sections that apply only to some funds open with what triggers them.
Short on time? Here's the gist
- The fund does not move. Its legal form, manager, depositary and valuation stay put. The unit register and the unit's operations go on-chain.
- One design choice decides most of the build. Open-ended or closed-ended settles the prospectus question, the liquidity tools and whether there is a redemption gate to build.
- The chain records. People decide. Classification, valuation, depositary oversight and regulator notifications stay human jobs.
- Tokenization does not create liquidity. A unit that can move still needs a buyer, and an illiquid open-ended fund has the same redemption problem on-chain.
Where to start, by role
| If you are | Read first |
|---|---|
| CEO, CPO or head of product | Why put fund units on-chain · What tokenization does not fix · Project stages |
| CTO or engineering lead | The life of a tokenized unit · Is the ledger the legal register · Decisions before scoping |
| Compliance lead | Which EU fund regime applies · Open-ended or closed-ended · Obligations that stay with you |
What is fund tokenization, and what does it leave unchanged?
Fund tokenization is the tokenization of the units of a fund. The token is the unit. It carries the same rights as a conventional unit, because those rights come from the fund rules, and the fund rules still apply in full.
Some people use the term for tokenizing what the fund owns, such as its buildings or loans. That is a separate project. This guide is about tokenizing the fund's units, the shares investors hold.
| Stays exactly where it is | Moves on-chain |
|---|---|
| The fund's legal form and the regime it sits under | The unit register, or a mirror of it |
| The manager's authorization | The record of every subscription, transfer and redemption |
| The depositary and its duties | Who may hold a unit, and when it may move |
| Valuation and the NAV calculation | The NAV figure, as signed by whoever calculates it |
| The fund rules and offering documents | Distribution runs |
| Your obligations to investors and the regulator | The audit trail that shows those obligations were met |
Three things a tokenized unit is not
- It is not the fund's assets. A holder owns a unit of the fund. They do not own a slice of a building, a loan or a bond.
- It is not a new instrument. The unit has exactly the rights the fund rules give it. The token cannot add any.
- It is not a liquidity promise. A token that can move between wallets is not necessarily a token anyone will buy, and it is not a unit the fund will redeem on demand.
Why would a licensed manager put fund units on-chain?
Managers tokenize funds to run them better. A ledger makes each benefit below possible, but none comes automatically. Whether the fund saves money overall depends on its size and how it runs today.
- Smaller minimum tickets. The manager sets the minimum, and units can be split further than most conventional registers handle comfortably.
- One record instead of several. The register, the transfer history and the distribution entitlements live in one place. So there is less reconciliation between administrator, transfer agent and distributor.
- Eligibility checked every time a unit moves. Investor type, jurisdiction, lock-ups and holding periods are tested on each transfer, not only at onboarding.
- Distributions that run from the register. The payout reads who held what on the record date and can be reproduced afterwards.
- A trail the depositary and regulator can read directly. They see the same record you do.
Tokenization also adds costs, including legal structuring, an independent audit, integration with your administrator and depositary, and running the platform.
What the market data says
The figures below are named fund products listed on RWA.xyz, as of 29 October 2026.
| Fund | Value on-chain |
|---|---|
| BlackRock USD Institutional Digital Liquidity Fund (BUIDL) | $2.19 billion |
| Spiko Amundi Overnight Swap Fund (EUR) | $1.80 billion |
| JPMorgan OnChain Liquidity-Token Money Market Fund (JLTXX) | $0.79 billion |
| WisdomTree Treasury Money Market Digital Fund (WTGXX) | $0.76 billion |
| Janus Henderson AAA CLO Fund (JAAA) | $0.57 billion |
| KKR Health Care Strategic Growth II Securitize Fund (SKHC) | $8.9 million |
| Hamilton Lane Secondary VI Securitize Fund (HLSF6) | $8.3 million |
| Partners Group Next Generation Infrastructure (NGI+) | $4.2 million |
Funds are already the common shape. Several of the largest tokenized Treasury products are units in a money market fund, not the bills themselves. RWA.xyz's Treasury category also holds products that are not fund units, so its category total is not a count of tokenized funds.
Tokenized funds now go beyond cash. Beyond money market funds, an overnight swap fund, a CLO fund and private equity funds are on-chain too. The private equity funds listed here, linked to KKR, Hamilton Lane and Partners Group, are each below $10 million.
The scale is still modest. The largest funds in this table hold between $0.57 billion and $2.19 billion each. Check the scope of any market forecast before you quote it, because some include stablecoins and tokenized deposits, which are not fund units.
Which EU fund regime governs a tokenized unit?
Applies if the vehicle pools investor money under a manager. If each investor holds a direct share of an asset with no manager discretion, AIFMD does not attach and this section does not apply.
A fund's regime decides who may manage it, whether a depositary must be involved, what has to be disclosed and which liquidity tools apply. Tokenization does not choose that regime. The fund's structure does, so identify it before you design anything.
Start with MiCA, because it is the most common wrong turn. MiCA does not apply to crypto-assets that qualify as financial instruments (Regulation (EU) 2023/1114, Art 2(4)(a)). Units in a collective investment undertaking are financial instruments under MiFID II (Directive 2014/65/EU, Annex I, Section C(3)). So a tokenized fund unit sits under fund law and MiFID II, not MiCA.
The fund regime then comes from one test and one default, run in order.
- Is it a UCITS? It must meet all four conditions at once: capital raised from the public, open-ended with redemption on demand, spread across investments, and invested only in liquid eligible assets (Directive 2009/65/EC). Real estate, commodities and loans are not eligible.
- If it fails any one, it is an AIF. An AIF is a vehicle that raises capital "from a number of investors, with a view to investing it in accordance with a defined investment policy for the benefit of those investors", and that is not a UCITS (Directive 2011/61/EU, Art 4(1)(a)). A fund is one or the other, never both.
- Does the AIF want a retail passport? ELTIF is an optional label on top of an AIF. It gives a long-term, illiquid fund an EU-wide marketing route that includes retail investors (Regulation (EU) 2015/760, as amended by Regulation (EU) 2023/606, applicable from 10 January 2024).
| Your fund | Regime | What it brings |
|---|---|---|
| Liquid eligible assets, open-ended, offered to the public | UCITS | A UCITS management company, eligible-asset limits, diversification rules |
| Pooled, not a UCITS, manager above the thresholds | AIFMD, full authorization | An authorized AIFM, a depositary, independent valuation, an EU passport |
| Pooled, manager below the thresholds | AIFMD, registration only | Lighter rules and no EU passport |
| Long-term illiquid AIF, retail passport wanted | AIFMD plus ELTIF | Full AIFMD authorization first, then each ELTIF authorized separately |
| Short-term assets with a money-market objective | Money Market Funds Regulation, on top of UCITS or AIFMD | See the money market section below |
The registration-only route is for a manager whose assets under management are €100 million or less with leverage, or €500 million or less without leverage and with a five-year lock-up.
Three misreadings come up most often.
- "Our investors are professional, so we cannot be a UCITS." The UCITS test is public offering versus private placement. It is not about investor category.
- "It is one asset, so it is not a fund." The number of assets is irrelevant. Pooling money under a manager's discretion decides it.
- "We used an SPV, so it is not a fund." A special purpose vehicle (SPV) changes who holds legal title. It does not change whether investors' money is pooled and managed.
Which branch a given structure lands on is for counsel to confirm. The build follows that answer. It does not supply it.
Open-ended or closed-ended: the choice that decides most of the build
Every fund is either open-ended or closed-ended, and the choice is usually made before anyone talks to a developer. Teams usually expect the asset class to drive the build. In practice, redemption design drives more of it than the asset does. Whether investors can redeem on demand decides three things at once.
The prospectus.
The Prospectus Regulation does not apply to units issued by collective investment undertakings other than the closed-end type (Regulation (EU) 2017/1129, Art 1(2)(a)). An open-ended fund is outside it. A closed-ended AIF is inside it. When the manager offers its units to the public or requests admission to a regulated market, it needs a prospectus or an exemption. Getting this backwards produces either a wasted prospectus or a missing one.
Liquidity management tools.
AIFMD II requires the manager of an open-ended AIF to select at least two liquidity management tools from the list in Annex V of AIFMD (Directive (EU) 2024/927). A UCITS has the equivalent under its own Directive. A closed-ended AIF needs none. The transposition deadline was 16 April 2026, and Member States may apply national measures from 16 October 2026. The application date is set nationally, so confirm the effective date in your home Member State.
A redemption mechanism.
An open-ended fund needs a way to take redemption requests, size what it can pay and treat everyone in the same window fairly. A closed-ended fund does not. That is one of the largest single pieces of the build, and it either exists or it does not.
| Open-ended | Closed-ended | |
|---|---|---|
| Prospectus Regulation | Outside. Disclosure runs through the fund rules | Inside. On a public offer or admission to a regulated market, a prospectus or an exemption |
| Liquidity management tools | At least two, selected and disclosed | Not required |
| Redemption gate in the contracts | Required | Not needed |
| PRIIPs KID if retail | Yes | Yes |
| Typical assets | Liquid securities, money market instruments | Property, private equity, infrastructure, credit |
Note the PRIIPs row. The redemption choice changes the prospectus answer but not the PRIIPs KID answer. That has its own trigger, covered under obligations below. ELTIFs are the exception on the prospectus row: every ELTIF publishes one under the ELTIF Regulation, whichever structure the manager chooses.
The life of a tokenized unit, step by step
Following one unit from subscription to redemption shows where the rules bite and what the build does about each. Steps that only exist in open-ended funds are marked. In every row, the left column is what the fund already has to do. The right column is one way to build it. No regulation prescribes a contract design.
| Step | What the fund has to do | What an on-chain build does |
|---|---|---|
| 1. Onboarding | Verify the investor and classify them for distribution | One verified identity per investor, bound to their wallets. Investor type and jurisdiction recorded as credentials that expire and can be revoked |
| 2. Subscription | Take in cash and issue units at the right price. For an AIF with a depositary, the depositary monitors the fund's cash flows (AIFMD Art 21) | Subscription and settlement tracked separately. Units stay pending and non-transferable until cash is confirmed, so the register never shows anything the depositary cannot reconcile |
| 3. Holding | Apply lock-ups and minimum holding periods in the fund rules | A holding-period check on the seller at the point of transfer |
| 4. Transfer | Let units move only to investors the fund rules and distribution rules allow | Every transfer is checked before it settles: eligibility, jurisdiction, lock-up, sanctions screening. A failed check refuses the transfer |
| 5. Valuation | Value the fund. The administrator or valuer calculates NAV | A NAV figure signed by the administrator, with checks for staleness and sudden deviation. The chain records NAV. It never calculates it |
| 6. Distribution | Pay income by class and entitlement | A payout run that reads the register at the record date and can be re-run to prove the result |
| 7. Redemption (open-ended only) | Redeem under the fund rules, using the selected liquidity management tools when needed | Requests collect in a dealing window. When it closes, one pro-rata ratio applies to everyone in it, and any unpaid remainder carries forward |
Two rows deserve a closer look.
Redemption fairness. "Select at least two liquidity tools" (an AIFMD II rule, covered above) says nothing about how a gate shares out what is available. First-come-first-paid turns a liquidity limit into a race, and the fund pays early redeemers out of value that belongs to those behind them. A single pro-rata ratio per window avoids that. It is a design choice, not a legal requirement, but it is the one we build because the alternative creates the dilution the tools exist to prevent.
NAV. Every limit and every redemption cap divides by NAV. A wrong or stale figure spreads into every calculation that reads it. That is why a NAV feed that halts on a bad figure is safer than one that publishes it.
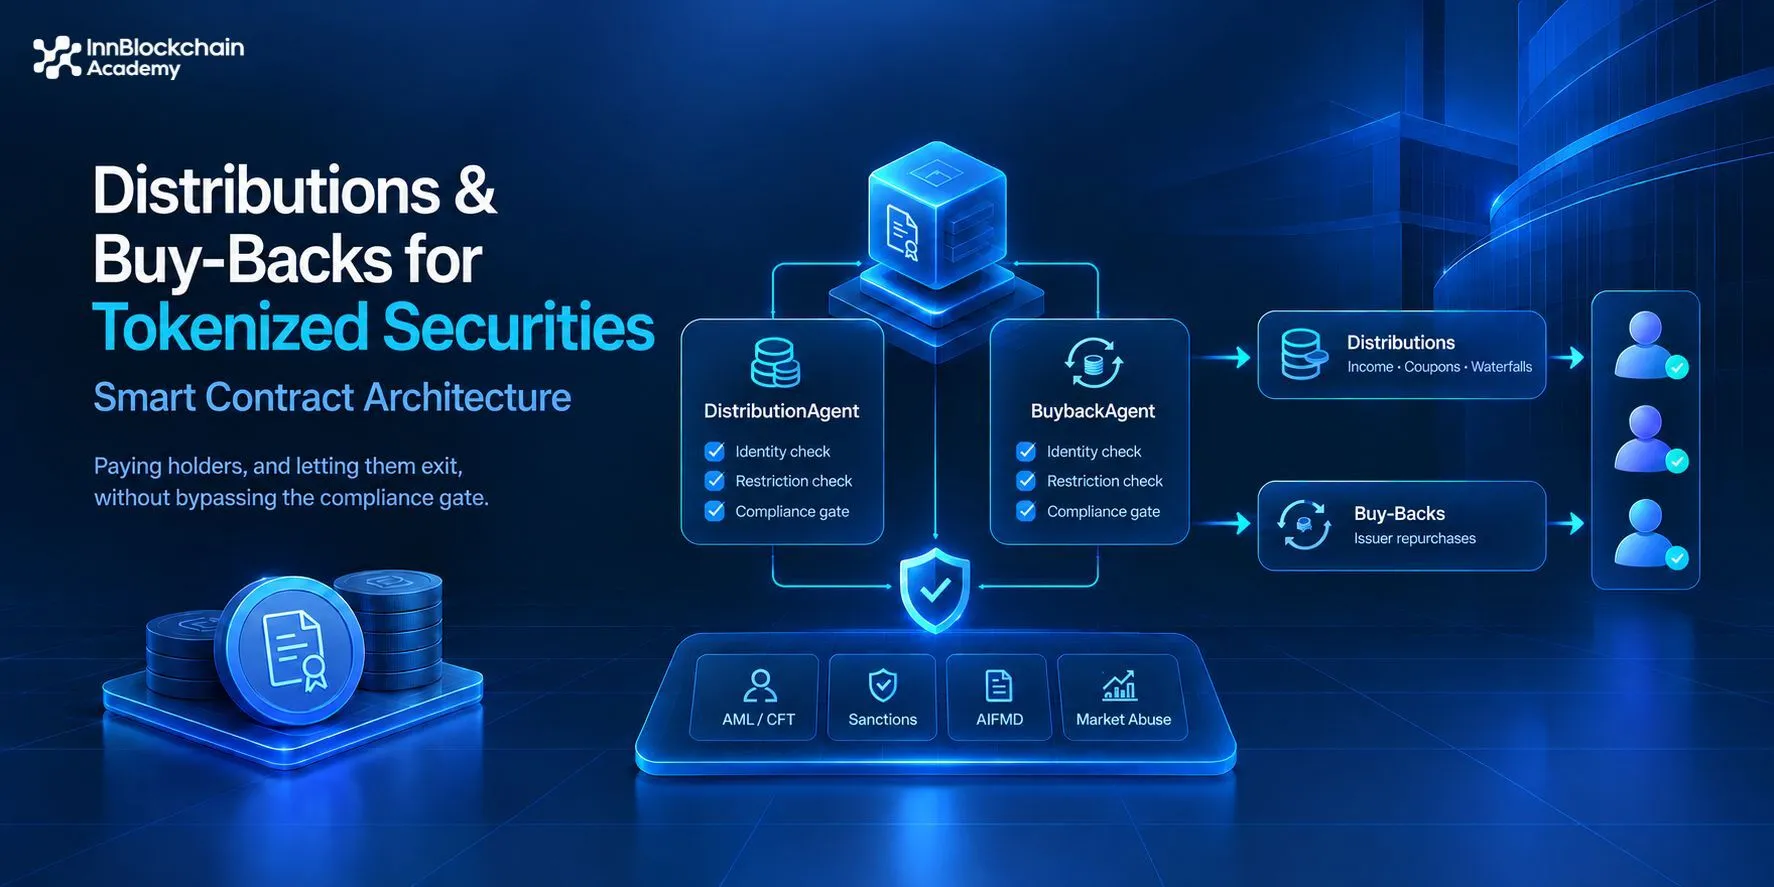
For the contract-level detail on concentration, liquidity and valuation, see our AIFMD, UCITS and ELTIF architecture deep-dive. For distributions and buy-backs, see our series article on distributions, coupons and buy-backs on-chain.
Who reads the register besides you?
A tokenized register has readers you do not control. Give them access from the first design, because changing a live register later costs far more.
| Reader | What they need from the record | What that means for the build |
|---|---|---|
| Depositary | Oversight of how units are issued, redeemed and valued, and a reconcilable view of cash (AIFMD Art 21) | A read interface the depositary queries directly, and distribution runs it can reproduce. Not a report someone compiles for it |
| Administrator | The register and the subscription and redemption flow, to strike NAV and process dealing | Events and data in a form its systems can take in without manual re-keying |
| Supervisor | Evidence the fund met its rules, and notice of certain events | A complete transfer history and events that make reportable moments visible. Filing stays a person's job |
| Auditor | Proof that each rule maps to code that enforces it | One module per rule, and a written map from obligation to module |
The supervisor row hides a practical point. Activating certain liquidity management tools is a notification event. The contract can make the moment unmissable. It cannot send the notification for you.
Is the ledger the legal register, or a copy of one?
Applies if the manager wants the token to be the legal record of ownership. If a conventional register stays the record, the token is a mirror and these questions are smaller.
This is the most consequential decision in the build, and national law makes it, not you. Some Member States have laws that let a distributed-ledger entry count as the legal record. Germany's electronic securities law (eWpG), France's DEEP framework and Luxembourg's blockchain laws are the best-known examples. Elsewhere, the legal register stays conventional.
That produces two different builds.
| The ledger is the register | The ledger mirrors the register | |
|---|---|---|
| What the token is | The unit itself | A digital copy of a unit recorded elsewhere |
| What a transfer does | Moves legal title | Triggers an update to the legal record |
| What the build must handle | The registry law's own demands: correction, recovery, and one authoritative record | Reconciliation between two records, and a rule for which one wins when they differ |
| Main risk | The ledger falls short of something the law requires of a register | The two records drift apart |
| How to reduce it | Counsel confirms the ledger meets that country's register rules before the build. The build includes the correction and recovery paths the law requires, and the audit tests them | The fund documents say which record wins. The two records are compared on a schedule, and any difference is investigated and fixed |
Whether a given country's law covers fund units, and on what terms, is a question for local counsel.
Does it work differently for money market, property and private equity funds?
Each subsection applies only if your fund is that type.
Money market and treasury funds
Applies if a UCITS or an AIF holds short-term assets and aims either for money-market returns or to preserve the value of the investment.
The Money Market Funds Regulation (Regulation (EU) 2017/1131) is an objective test. You cannot opt out by calling the fund something else. The manager may not establish, market or manage a fund with those objectives and assets of two years or less residual maturity in the Union unless the fund holds authorization as a money market fund (Art 4(1)).
Two rules shape a token design. A money market fund may not receive outside support from a sponsor (Art 35), so a token that needs a sponsor to hold its value is not a money market fund unit and needs its own classification analysis. And redemption cannot be unconditional, because the board must be able to apply fees, gates or suspensions in set conditions (Art 34).
Property funds
Applies if a fund pools investor money to invest in property, with a manager deciding what it buys and sells.
A property fund is usually a closed-ended AIF, because real estate is not a UCITS-eligible asset. If the manager wants to market to retail investors across the EU, the ELTIF label is the route, and it needs full AIFMD authorization first.
An ELTIF is not always closed-ended. Since ELTIF 2.0 (Regulation (EU) 2023/606), a manager may let investors redeem during the fund's life, within limits the Regulation sets: a minimum holding period, a redemption policy disclosed upfront, and redemptions capped by the fund's liquid assets. That brings back the redemption mechanics described in the open-ended section. Either way, an ELTIF publishes a prospectus under its own Regulation (Art 23).
An ELTIF marketed only to professional investors gets relief from the diversification and concentration limits. The restriction has to be written into the fund rules and the prospectus. It is a documented constraint, not a marketing choice.
The hard part on-chain is valuation. Property is valued by appraisal, not by a market price. The NAV is a dated figure from an independent valuer, and the investor portal should show its date and source so a holder can see how old it is.
Private equity, infrastructure and private credit funds
Applies if the fund is a closed-ended pool that calls capital over time, has share classes with different rights, or originates loans.
These are usually closed-ended AIFs, so there is no redemption gate to build. The work moves elsewhere:
- Capital calls and drawdowns, where investors commit an amount and pay it in over time.
- Classes with different rights, which need separate compartments on the register.
- A distribution waterfall, which decides who is paid first and must match the fund documents exactly.
Funds that lend also fall under the AIFMD II loan-origination rules. A loan-originating AIF must be closed-ended by default, and an AIF that originates a loan and then sells it on must keep at least 5% of it.
Tokenizing a company's own shares is a different project from tokenizing a private equity fund. For that, see private equity tokenization.
Which obligations stay with you after the unit becomes a token?
Each row applies only when its trigger is met. No fund owes all of them.
Tokenization removes no obligation. It changes how some are evidenced.
| Rule | Attaches when | What changes for a tokenized unit |
|---|---|---|
| AIFMD or UCITS | The fund falls within either | Nothing legally. The depositary gets a read interface and sees subscription state |
| MiFID II conduct and product governance | Anyone distributes the units | The target market and the negative target market can be written as eligibility rules the contract checks |
| Prospectus Regulation | A closed-ended fund is offered to the public with no exemption | See the open-ended or closed-ended section |
| PRIIPs KID | A retail investor is anywhere in the distribution chain. A fund unit counts as a packaged product (Regulation (EU) No 1286/2014) | The KID must reach the investor before they are bound, so it becomes a step in onboarding, not an attachment to the confirmation |
| Market Abuse Regulation | The units are admitted to trading on a venue, including someone else's, or admission is requested | Insider-information duties attach to the units |
| Anti-money-laundering rules | The manager is an AIFM or UCITS management company | The AML Regulation (Regulation (EU) 2024/1624) applies from 10 July 2027. National rules apply until then |
| DORA | The manager is an authorized AIFM or UCITS management company (Regulation (EU) 2022/2554, Art 2) | Your platform vendor is an ICT third-party provider, and the contract with it has to carry the required terms. A registration-only AIFM is excluded (Art 2(3)) |
| GDPR | Always, for investor personal data | Personal data stays off-chain, because a public ledger cannot erase it |
Two of these catch people out.
A prospectus exemption is not a KID exemption. The two regimes have separate triggers. Offering only to professional investors removes both. Other prospectus exemptions leave the KID duty untouched.
DORA flips at the threshold. A manager that crosses from registration to full authorization moves into DORA. If that crossing is in your raise plan, the vendor contract should be ready for it before it happens.
On GDPR, our GDPR deep-dive explains how the right to erasure collides with record-keeping duties and how to design around it.
What should an engineering lead decide before scoping a build?
Applies once the regime and the register question are settled.
Every decision below is a design choice. No EU regulation names a token standard, an oracle design or a contract architecture.
| Decision | Why it cannot wait | The usual options |
|---|---|---|
| Token standard | It decides what you get ready-made and what you write yourself | ERC-3643 specifies identity and modular compliance but has no partitions, so share classes need custom work. ERC-1400 specifies partitions but not identity. See our ERC-3643 vs ERC-1400 comparison |
| Identity and eligibility | Rules attach to people, not wallets, and an investor's status can lapse | One identity registry, credentials that expire, scheduled re-verification |
| Register of record | It decides what the audit has to prove | The two builds above |
| NAV feed | Every limit and redemption cap divides by it | The administrator signs it directly, or an external source sits behind a guard that halts on a bad figure |
| Redemption mechanism | It decides whether investors race for liquidity | A dealing window with one pro-rata ratio, or none for a closed-ended fund |
| Change control | Rules and parameters change after launch | Compliance rules in replaceable modules behind a time delay. Parameters that need notice to a regulator should not change on a vote alone |
| Integrations | The chain is a small part of the fund's operations | Administrator, depositary, transfer agent, KYC provider, and how cash moves |
| Audit | A fund unit is a regulated financial instrument | An independent audit that tests compliance logic as well as exploits |
Each of these is a decision we settle at scoping. Our STO development for authorized firms page shows how the token, register and compliance modules are built.
What stages does a fund tokenization project go through?
Six stages. They overlap, but the first two almost never change order.
- Structure. With counsel, settle the fund regime, open-ended or closed-ended, the offer route, the investor base and where the legal register sits.
- Specification. Map each obligation to the module that enforces it. Compliance signs off the map before any code is written.
- Build. Contracts, investor portal, issuer tooling, and the integrations with the administrator and depositary.
- Review and audit. An internal security review, then an independent audit by a firm that did not write the code. Findings are fixed and re-tested.
- Documents and filings. Prospectus or exemption, KID, fund rules and any authorization, all ready before the first investor subscribes.
- Launch and run. Mainnet deployment, monitoring, onboarding and the first distribution.
There is no honest single timeline. The build is often the shorter part. Authorization reviews, document approvals and investor onboarding set the pace, and some have statutory review windows of their own. An ELTIF, for example, is authorized fund by fund by its home regulator. Ask any provider to split its plan into legal, build and onboarding steps, and to show the regulator's time separately from its own.
What should a licensed manager have in place before starting?
Seven things. A gap in any one of them stalls the project, usually at stage 1 or 5.
- A settled fund structure, with counsel's view on the regime, open-ended or closed-ended, and the offer route.
- An administrator that calculates NAV and can sign a feed.
- A depositary willing to read the on-chain record.
- A registrar or transfer agent arrangement, so it is clear who keeps the legal register.
- Investor onboarding, with a KYC provider and settled investor categories.
- A compliance function that can approve a technology vendor and its ICT risk.
- An internal owner for the platform after handover.
What does tokenization not fix?
Say this before the board asks.
It does not create liquidity. A token needs a buyer, and a buyer needs a venue and a price they trust. Admitting units to a trading venue brings the Market Abuse Regulation with it, and running a venue needs its own authorization.
It does not fix a liquidity mismatch. An open-ended fund holding illiquid assets has the same redemption problem on-chain. The answer is the fund's design and its liquidity management tools, not the ledger.
It does not solve valuation. A chain cannot see the world. The NAV is only as good as the administrator or valuer who signs it and the feed that carries it.
Where to go from here
Tokenizing a fund leaves the hard parts of running one where they were. Classification, valuation, the depositary and investor protection still decide whether the fund works. What changes is how the unit is recorded, held and moved. If you can already answer three questions (which regime, open-ended or closed-ended, and which register), you are further along than most. And If not, start there.
If you are scoping a tokenized fund, our tokenization development for authorized firms covers the token, the register, the compliance modules, investor and issuer tooling, and the independent audit. And If you are mapping a fund onto a tokenized structure, book an architecture review.
If you need the regulation first. The EU tokenization regime guide maps MiFID II, the Prospectus Regulation, AIFMD and MAR to what the platform has to enforce.
If your asset is not a fund. A single property, loan or bond with no pooled capital follows a different path. See RWA tokenization development.
Frequently asked questions
What is fund tokenization for a licensed asset manager?
It is issuing and recording a fund's units as tokens on a blockchain while the fund stays the same. The manager, depositary, valuation and investor rights do not change. The unit register and the unit's operations move on-chain.
How is fund tokenization different from a crypto-native protocol?
A protocol writes its own rules. A licensed manager inherits fund law, MiFID II and its own fund rules, and the token has to enforce them. Most of the work is the fund's operations, not the token.
How does fund tokenization work under MiFID II?
A fund unit is a financial instrument under MiFID II, so the token is one too and MiCA does not apply. The fund regime governs the manager. MiFID II conduct and product governance rules govern whoever distributes the units.
Does a tokenized fund need a prospectus?
It depends on redemption design. Open-ended funds are outside the Prospectus Regulation. Closed-ended AIFs are inside it and, on a public offer or admission to a regulated market, need a prospectus or an exemption. A retail offer also needs a PRIIPs KID either way.
What stages does a fund tokenization project go through?
Structure, specification, build, review and audit, documents and filings, then launch. Counsel and compliance lead the first two. Engineering leads build and audit.
How long does a fund tokenization project take?
There is no single honest figure. The build is often the shorter part. Authorization reviews, document approvals and investor onboarding set the pace. Ask for a plan that separates legal, build and onboarding time.
What should a licensed asset manager have in place before starting?
A settled fund structure, an administrator that can sign a NAV feed, a depositary willing to read the on-chain record, a registrar arrangement, investor onboarding, a compliance function that can approve the vendor, and an internal owner after handover.
Does tokenizing a fund make its units liquid?
No. Tokenization changes how units are recorded and moved. It does not create buyers, a venue or a trusted price. Redemption liquidity still depends on the fund's assets and its liquidity management tools.
Does MiCA apply to a tokenized fund unit?
No. MiCA does not apply to crypto-assets that are financial instruments (Art 2(4)(a)), and a fund unit is one. Fund law, MiFID II and, for closed-ended funds, the Prospectus Regulation apply instead.
This is engineering commentary on regulatory requirements, not legal advice. Whether and how these rules apply to a specific fund or structure needs sign-off from counsel.